Blog

What to Do After a Car Accident That’s Not Your Fault in New York: Steps and Compensation
what to do after a car accident not your fault
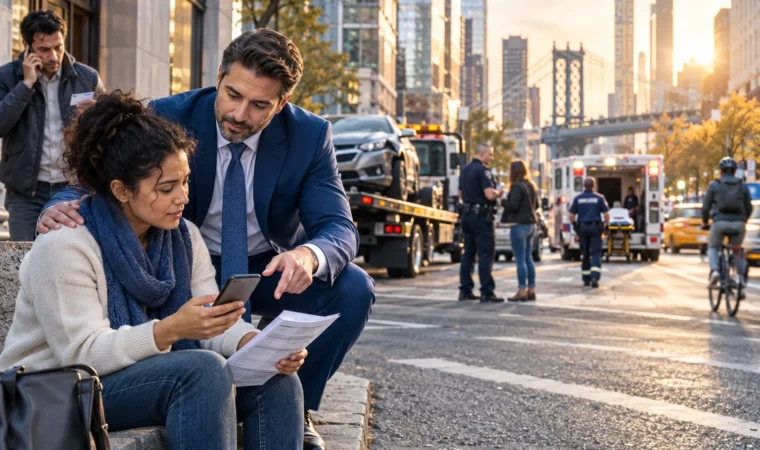
If you are deciding what to do after a car accident not your fault, first protect everyone at the scene, call the police, exchange information, document what happened, and get medical care. New York’s no-fault rules generally direct you to seek initial medical and wage benefits through your own auto insurer, even when another driver caused the crash.
Key Takeaways
- Even when another driver caused your crash, New York’s no-fault insurance system means your own auto insurer pays your first medical bills and lost wages.
- Calling the police to the scene creates an official report that becomes critical evidence when you pursue compensation from the at-fault driver.
- See a doctor promptly, even if your injuries seem minor, because delayed treatment gives insurance adjusters ammunition to dispute your claim.
- Photograph the vehicles, the scene, and your injuries, and collect contact and insurance details from every driver and witness before you leave.
- Before accepting any quick settlement offer, speak with an experienced New York car accident attorney to make sure your full damages are covered.
At Silberstein & Miklos, P.C., our work in New York injury cases shows why accurate records matter: insurers review collision details, medical treatment, and claim paperwork. Follow these steps, and do not sign a release before you understand what it covers.
What Should You Do Immediately After a Car Accident That Is Not Your Fault?
Check for injuries and move away from traffic if safe. Call 911 if anyone is hurt or the scene creates a safety risk. Exchange driver, vehicle, and insurance details, save photos and witness information, and arrange medical care. Report the crash to your insurer promptly: New York no-fault benefits have a short filing deadline.
Step 1: Check for Injuries and Move to Safety
Check yourself, passengers, and others for injuries. Call 911 if anyone needs urgent help. Do not move an injured person unless staying put creates immediate danger. Move vehicles out of traffic if safe; otherwise, wait in a protected location for help. Turn on hazard lights when possible.
Step 2: Call the Police and Get a Report
Call police after a crash involving injuries, significant vehicle damage, or disagreement about what happened. New York Vehicle and Traffic Law requires a driver to report a crash to police when someone is injured or killed. A police report may record drivers’ accounts, witnesses, and visible conditions, but it does not decide legal fault. Ask how to get the report and keep its incident details.
Step 3: Exchange Information With the Other Driver
Get the other driver’s name, address, phone number, license plate, driver’s license details, and insurance company and policy information. Provide your required details. Keep the exchange calm and factual. Do not argue about fault or guess about injuries; insurers may later repeat statements made at the scene. If the other driver leaves or refuses to share information, tell the responding officer.
Step 4: Document the Scene With Photos and Witnesses
If safe, photograph vehicles before they are moved. Capture damage from several angles, license plates, traffic signals, road conditions, debris, skid marks, and the wider intersection or roadway. Save dashcam footage and note the time, location, weather, and direction of travel. Ask witnesses for contact details. These records preserve evidence before repairs or fading memories make it harder to establish what happened.
Step 5: See a Doctor Even If You Feel Fine
Arrange a medical evaluation promptly, even if pain is mild or delayed. A clinician can assess symptoms and record their connection to the collision. Describe where you hurt and how symptoms change; do not downplay them. Follow the treatment plan and keep appointment summaries, bills, prescriptions, and work-absence records. If helping an injured family member, keep copies together.
How Does New York’s No-Fault Insurance Affect Your Claim?
New York requires no-fault auto coverage, also called Personal Injury Protection (PIP). PIP generally pays eligible medical expenses and part of lost earnings after a crash, regardless of fault, subject to policy terms and limits. PIP can help with early bills, but does not automatically pay every loss or pain and suffering.
Who Pays Your Medical Bills and Lost Wages Right Now
For initial injury benefits, notify the insurer handling the applicable no-fault coverage, often your own auto insurer. PIP may cover eligible medical care and lost wages within policy limits. It does not pay to repair your vehicle; property-damage claims generally go through the at-fault driver’s liability insurer or your applicable coverage. Ask insurers which forms and records they need, and keep copies of submissions.
No-Fault vs. At-Fault Claims: What Changes in New York
| Claim route | What it generally addresses | Key point |
|---|---|---|
| No-fault, or PIP | Eligible medical expenses and lost earnings | Benefits are subject to policy terms, limits, and filing rules. |
| At-fault driver’s liability coverage | Injury losses that may be pursued outside PIP, when legal requirements are met | Fault and the serious injury threshold can affect an injury lawsuit. |
| Vehicle property-damage claim | Repair or replacement losses for the car | This is separate from no-fault injury benefits. |
The Serious Injury Threshold: When You Can Sue the At-Fault Driver
New York Insurance Law limits lawsuits for pain and suffering from motor vehicle crashes. To pursue these non-economic damages, an injured person generally must prove a “serious injury” under the law. Categories include a fracture, significant disfigurement, or permanent loss of use of a body organ or function. The legal test depends on medical evidence and the facts. Have a lawyer assess your records before assuming you qualify or do not qualify.
Why You Must Notify Your Own Insurance Company Within 30 Days
New York no-fault rules generally require written notice of an injury-benefit claim within 30 days of the crash, subject to limited exceptions. Missing the deadline can put benefits at risk. Report the collision promptly, complete the required application, and retain proof of submission. If unsure which insurer must receive the paperwork, get guidance rather than waiting for the other driver’s insurer.
What Compensation Can You Recover After a Not-At-Fault Accident in New York?
Possible recovery depends on injuries, insurance coverage, proof of losses, and whether you meet New York’s serious injury threshold for a pain-and-suffering lawsuit. No-fault benefits may pay eligible medical expenses and part of lost earnings within policy limits. A separate claim against the at-fault driver may address losses PIP does not cover, if legal requirements are met.
Economic Damages: Medical Bills, Lost Wages, and Property Damage
Economic damages are financial losses supported by bills, receipts, pay records, and repair estimates. Depending on coverage and the claim, they may include medical expenses, lost income, and vehicle repair or replacement costs. Keep records of treatment, prescriptions, transportation to appointments, missed work, and vehicle damage. One insurer may not pay every category of loss.
| Loss | Records to keep | How it may be addressed |
|---|---|---|
| Medical care | Medical bills, treatment notes, prescriptions | No-fault benefits may cover eligible expenses within policy terms and limits. |
| Lost earnings | Pay stubs, employer statements, missed-work dates | No-fault may pay part of lost earnings; other recovery depends on the claim and applicable law. |
| Vehicle damage | Photos, repair estimates, invoices, rental receipts | A property-damage claim is separate from no-fault injury benefits. |
Non-Economic Damages: Pain and Suffering
Pain and suffering means physical discomfort and personal impact, rather than a bill or lost paycheck. New York generally requires proof of a qualifying serious injury to seek these damages after a motor vehicle crash. A fracture, significant disfigurement, or permanent loss of use may fit statutory categories, but the medical evidence and facts matter. A diagnosis alone does not establish that the legal threshold is met.
Comparative Negligence: How Your Share of Fault Reduces Your Recovery
New York follows pure comparative negligence: an injured person can recover damages even when partly responsible for a crash, but the award is reduced by that person’s share of fault. If insurers dispute events, preserve photos, witness details, vehicle damage evidence, and medical records. Have counsel review the evidence before accepting an unsupported fault decision.
Uninsured or Underinsured Drivers: How SUM Coverage Protects You
Supplementary uninsured/underinsured motorists coverage, known as SUM, can provide added protection when the at-fault driver has no insurance or insufficient coverage, subject to policy terms and limits. New York requires baseline uninsured motorist coverage; drivers can purchase SUM coverage for additional protection. Review your declarations page for limits and notice requirements. Silberstein & Miklos, P.C. provides Construction Accident Legal Services for construction injury matters, separate from motor vehicle claims. Construction Accident Legal Services does not determine your auto policy benefits.
Common Mistakes That Reduce Compensation After a Not-At-Fault Accident
Insurers assess timely notice, consistent records, and evidence supporting claimed losses. Avoid gaps or closing off options before understanding the consequences. If pain, paperwork, or work makes claim management difficult, ask a trusted family member to organize records and track insurer communications.
Waiting Too Long to File Your No-Fault Claim
New York generally requires written notice of a no-fault injury claim within 30 days of the crash, subject to limited exceptions. Delay can put treatment and lost-earnings benefits at risk. Send the required application promptly, keep a copy, and save proof of delivery or submission. If unsure which insurer handles the claim, get guidance instead of waiting for the other driver’s insurer.
Giving a Recorded Statement to the Other Driver’s Insurer
The at-fault driver’s insurer may request a recorded statement before you have gathered facts or completed care. Do not guess about speed, distance, or the cause of an injury. Ask what information the adjuster needs and speak with a lawyer before agreeing to a recorded interview. Keep communications factual and retain letters, emails, and claim numbers.
Accepting a Quick Settlement Before You Know Your Full Injuries
A settlement release can end your claim for losses covered by its terms. Signing before doctors understand your recovery needs can leave future treatment costs or lasting effects unpaid. Read every release and do not sign until you know which claims it closes and what compensation it provides.
Downplaying Your Pain to Doctors and Adjusters
Give clinicians an accurate account of symptoms, limits, and changes over time. Explain how pain affects sleep, walking, lifting, driving, and work. Consistent medical records show the injury and care required. Never exaggerate, but do not minimize symptoms to appear resilient.
How Long Do You Have to File a Claim, and When Should You Call a Lawyer?
In New York, most personal injury lawsuits must be filed within three years of the accident. That deadline does not extend the separate 30-day deadline for notifying an insurer about a no-fault claim. Contact a lawyer early for serious injuries, disputed fault, or insurance questions. Silberstein & Miklos, P.C. brings decades of trial experience and AV-rated legal excellence to New York injury cases.
New York’s Three-Year Deadline (CPLR 214) in Plain Language
CPLR 214 sets a general three-year deadline from the date of injury for filing many personal injury lawsuits. This statute of limitations is the legal time limit for starting a lawsuit. Missing it can end your right to pursue the case, even with strong evidence. Different rules may apply to claims involving public entities, and other exceptions can affect the deadline. Check your case facts rather than assuming you have three years.
Insurance claims and lawsuits have different timelines. An insurance claim does not automatically preserve your right to sue. If a city, county, or other public entity may be responsible, ask a lawyer promptly about notice requirements and shorter deadlines. Action: Record the accident date and get legal advice early, especially if a government vehicle or roadway may be involved.
A Timeline From Accident to Settlement
A claim’s pace depends on medical recovery, evidence, insurance issues, and disputes about responsibility. Keep records organized. A settlement should reflect documented losses and known injury effects, not merely the speed of the insurer’s offer.
- Early stage: Report the crash, submit required insurance paperwork, and gather treatment, work, and vehicle-damage records.
- Medical treatment: Follow your care plan and record appointments, symptoms, and expenses. Medical progress helps clarify the claim’s value.
- Claim review: The insurer reviews evidence and may dispute fault, coverage, or losses. Your lawyer can address disputes and present supporting records.
- Resolution: The parties may negotiate a settlement. If they cannot reach an acceptable agreement, a lawsuit may be necessary before the filing deadline.
When to Hire a New York Car Accident Lawyer
Speak with a lawyer promptly if your injuries are serious, an insurer disputes your account, the other driver lacks enough coverage, or you face pressure to sign a release. Guidance also helps when treatment continues or a public entity may be involved. A lawyer can review deadlines, coverage, medical documentation, and evidence before you make decisions affecting your claim. Silberstein & Miklos, P.C. provides Expert legal representation and has Experience with million-dollar settlements. Past results do not guarantee a future outcome.
Frequently Asked Questions
Should I file a claim with my insurance if I'm not at fault?
Yes. In New York, no-fault rules require you to report the crash to your own insurer for Personal Injury Protection (PIP) benefits, which cover eligible medical expenses and part of lost wages regardless of fault. Notify your insurer in writing within 30 days or your benefits may be at risk.
What happens if you crash and it's not your fault?
Even when another driver caused the crash, you should check for injuries, call 911, exchange information, photograph the scene, and see a doctor promptly. Your own insurer handles initial no-fault benefits, and a separate property-damage claim goes through the at-fault driver’s liability insurer.
What should you not say when making an insurance claim?
Do not guess about fault, admit blame, or downplay your injuries to any insurer. Adjusters may repeat statements you made at the scene. Stay calm, stick to the facts, and do not sign a release before you understand what it covers.
How much are most car accident settlements?
Settlement amounts depend on the facts of each case: the severity of your injuries, medical costs, lost wages, and available insurance coverage. No attorney can promise a specific figure. An experienced New York injury lawyer can evaluate your records and pursue the maximum compensation your case supports.
How much will my insurance go up after a non-fault accident?
There is no fixed increase after a non-fault accident; rate changes depend on your insurer, your driving record, and your policy terms. Because New York no-fault benefits come through your own insurer, report the crash promptly and ask your carrier how a claim may affect your premium.
Do I need to see a doctor after a car accident if I feel fine?
Yes. Some injuries cause pain that appears hours or days later. A prompt medical evaluation records the connection between your symptoms and the collision, which insurers and courts rely on. Describe your symptoms fully and keep every appointment summary, bill, and prescription.
Can I sue the at-fault driver in New York?
You can sue the at-fault driver for pain and suffering only if you meet New York’s serious injury threshold, which includes categories like a fracture, significant disfigurement, or permanent loss of use of a body organ or function. A lawyer should review your medical records before you assume you qualify.
